 exuber
Heteroskedasticity-robust (time-transformed)
Monte Carlo critical values for the time-transformed test (STADF/GSTADF)
radf_tt_cv radf_tt_cv(n, minw = NULL, nrep = 2000L, seed = NULL)This is the dedicated critical-value function for radf_tt. It simulates the asymptotic null distribution of the GLS-demeaned recursive sup-ADF statistic that radf_tt uses. By Theorem 1 of Kurozumi, Skrobotov & Tsarev, this distribution is free of the volatility process (pivotal). Unlike radf_wb_cv, it therefore does not have to be recomputed for each dataset. A large n with the default nrep approximates well the T -> Inf limit used in the paper.
Arguments
| n | A positive integer. The sample size. |
| minw | A positive integer. The minimum window size (default = , where T denotes the sample size). |
| nrep | A positive integer. The number of Monte Carlo simulations. |
| seed | An object specifying if and how the random number generator (rng)
should be initialized. It is either NULL or an integer, which is passed to
set.seed before the simulation. If you set it, the value is saved as the
"seed" attribute of the returned value. The default, NULL, leaves the state of
the rng unchanged and returns .Random.seed as the "seed" attribute. Results are
reproducible across the parallel and the non-parallel option when you use the
same seed. |
Value
An object of class radf_cv/tt_cv/mc_cv with the same structure as radf_mc_cv: the scalars adf_cv, sadf_cv and gsadf_cv for each level plus the sequences badf_cv and bsadf_cv. You can use it wherever a radf_cv is accepted.
Details
You can check the sadf_cv column (STADF, that is, r1 = 0 fixed) against the asymptotic values of Whitehouse (2019) quoted in footnote 4 of Kurozumi, Skrobotov & Tsarev. For minw/n = 0.1, the values at (10\%, 5\%, 1\%) are (2.319, 2.626, 3.223). This published triple is for STADF and not for GSTADF (gsadf_cv). The paper gives its GSTADF critical values not as numbers in the text but only as "easily computed from" the code of the authors in R.
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
cv <- radf_tt_cv(n = 200, minw = 20)
tidy(cv)
#> # A tibble: 3 × 4
#>   sig     adf  sadf gsadf
#>   <fct> <dbl> <dbl> <dbl>
#> 1 90    0.876  2.25  3.28
#> 2 95    1.22   2.61  3.58
#> 3 99    1.91   3.21  4.40

# Volatility triples half-way through the sample. This is the case of
# non-stationary volatility that this test is built for, and plain radf()
# over-rejects here
y <- sim_psy1(n = 200, seed = 1, e = sim_vol_break(199))
res <- radf_tt(y, minw = 20)
datestamp(res, cv = cv)
#>
#> ── Datestamp (min_duration = 0) ───────────────────────── Time-Transformed MC ──
#>
#> series1 :
#>   Start Peak End Duration   Signal Ongoing
#> 1    21   38  89       68 negative   FALSE
#> 2   148  148 149        1 positive   FALSE
autoplot(res, cv = cv)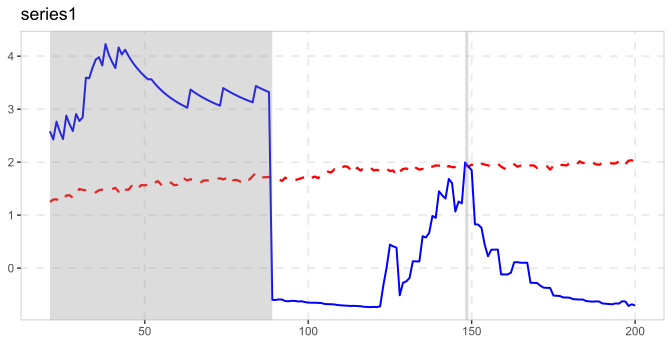
See also
Other critical values: radf_common_cv(), radf_mc_cv(), radf_recovery_cv(), radf_sb_cv(), radf_sbz_cv(), radf_sign_cv(), radf_sign_dm_cv(), radf_wb_cv(), radf_wb_ps_cv()
References
Kurozumi, E., Skrobotov, A., & Tsarev, A. (2024). Time-Transformed Test for Bubbles under Non-stationary Volatility. Journal of Financial Econometrics. 10.1093/jjfinec/nbae026