 exuber
Real-time monitoring
Locally Best Invariant Test for a Bubble (Breitung & Diegel 2025)
lbi_test
Replication record →
lbi_test(data, sig_lvl = 95)lbi_test implements the static locally best invariant (LBI) test of Breitung & Diegel (2025) for a bubble that is known, or assumed, to span the entire sample: LBI = (y_T - y_1) / (sigma_tilde * sqrt(T - 1)), where sigma_tilde^2 is the sample variance of the first differences. The test is robust to heteroskedasticity by construction, because the invariance property of the statistic does not depend on the exact form of the innovation variance. The null distribution is standard normal, so the test needs no bootstrap, no simulation and no published table.
Arguments
| data | A univariate or multivariate numeric time series object, a numeric
vector or matrix, or a data.frame. A column may have leading or trailing
NA values, which describes an unbalanced panel in which series enter or
exit the sample at different times. Those periods are filled with NA in
badf and bsadf and excluded from the adf, sadf and
gsadf of that series. Interior NA values (a gap in the middle of
a series) are not supported. When any series is padded in this way, the panel
statistics (bsadf_panel and gsadf_panel) are not available, and
the function returns NA for them with a warning. |
| sig_lvl | Significance level of the one-sided, right-tailed test (positive
bubbles only), on the 0 to 100 scale used throughout the package (default
95). Any value in [50, 100) is accepted, because the critical
value is a closed-form normal quantile. |
Value
An object of class lbi_test_obj: a list with the test statistic stat, the standard-normal critical value crit and detected (logical, stat > crit).
Details
Only the static test, which uses a single full-sample window, is implemented. The main contribution of Breitung & Diegel is a sequential, exponentially weighted extension for monitoring a series when the start date is unknown. Its exact weighting scheme and boundary constant are not pinned down here, so this function does not implement it.
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
y <- sim_psy1(n = 60, te = 1, tf = 60, seed = 1) # explosive from the start
res <- lbi_test(y)
print(res)
#>
#> ── lbi_test (n = 60, sig_lvl = 95%) ────────────────────────────────────────────
#>
#>    series   stat   crit  detected
#>   series1  4.892  1.645      TRUE

# Compare the statistic to its critical value
autoplot(res)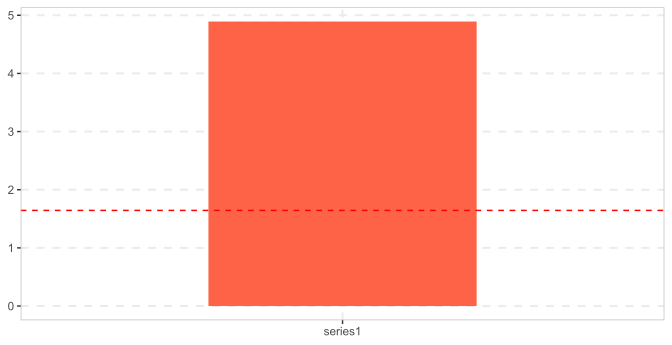
See also
radf for the recursive ADF-family alternative that this test complements.
Other alternative tests: quantile_test()
References
Breitung, J., & Diegel, M. (2025). A locally best invariant sequential test for explosive behavior in the presence of nonstationary volatility. Journal of Time Series Analysis.