 exuber
Real-time monitoring
CUSUM Real-Time Monitoring for Explosive Bubbles
monitor_cusum
Replication record →
monitor_cusum(
  data,
  r_star = 0.5,
  b_alpha = 4.6,
  boundary = c("asymptotic", "finite"),
  sig_lvl = 95,
  type = c("standard", "kernel"),
  h = 20,
  kernel = c("gaussian", "uniform")
)
monitor_cusum implements the CUSUM real-time monitoring procedure of Homm & Breitung (2012). You fix a training window [1, T*] that is assumed free of exuberance. The function then compares the standardized cumulative sum of the post-training first differences, S_t = (y_t - y_{T*}) / sigma_hat_t, with the closed-form boundary c_t * sqrt(t), where c_t = sqrt(b_alpha + log(t / T*)), and flags the first date at which the boundary is breached.
Arguments
| data | A univariate or multivariate numeric time series object, a numeric
vector or matrix, or a data.frame. A column may have leading or trailing
NA values, which describes an unbalanced panel in which series enter or
exit the sample at different times. Those periods are filled with NA in
badf and bsadf and excluded from the adf, sadf and
gsadf of that series. Interior NA values (a gap in the middle of
a series) are not supported. When any series is padded in this way, the panel
statistics (bsadf_panel and gsadf_panel) are not available, and
the function returns NA for them with a warning. |
| r_star | The end of the training window: a fraction in (0, 1) of the
sample (default 0.5), or an integer number of observations if
>= 1. |
| b_alpha | The boundary constant (eq. 29 of HB). The default 4.6 is the
one-sided asymptotic calibration of HB for a 5\% significance level (their
Section 3). It is an asymptotic upper bound on the false-alarm probability (Chu,
Stinchcombe & White 1996) and not an exact size, so it is typically conservative
in finite samples. It is ignored when boundary = "finite". |
| boundary | "asymptotic" (default) uses b_alpha directly.
"finite" instead looks up the finite-sample boundary constant of HB (their
Table 8) from sig_lvl and the realized ratio of training length to
monitoring horizon. sig_lvl must then be one of 90, 95 or
99. |
| sig_lvl | Significance level on the 0 to 100 scale used throughout the
package when boundary = "finite" (default 95). It is ignored when
boundary = "asymptotic". |
| type | "standard" (default) for the original CUSUM statistic of Homm
& Breitung (2012), or "kernel" for the volatility-robust "CUSUMV" variant
of Astill, Harvey, Leybourne, Taylor & Zu (2023). |
| h | Bandwidth (window length, N in AHLTZ) of the one-sided kernel
spot-variance estimator when type = "kernel". The default 20 is the
value that the authors recommend from their experiments (their Section 3:
"setting H = 20 delivered a procedure with the best trade-off" between
robustness of the false-alarm rate and power). It is ignored when
type = "standard". |
| kernel | Kernel for the spot-variance estimator when type = "kernel",
"gaussian" (default) or "uniform". It is ignored when
type = "standard". |
Value
An object of class monitor_cusum_obj: a list with the statistic path in the monitoring region (S) and boundary, the length of the training window T_star, and alarm and alarm_date (the first breach, NA if there is none).
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
# A martingale training window, explosive from t = 150 to the sample end
y <- sim_psy1(n = 200, te = 150, tf = 200, seed = 7)
res <- monitor_cusum(y, r_star = 0.5)
print(res) # alarm should fire soon after t = 150
#>
#> ── monitor_cusum (T* = 100 / 200, b_alpha = 4.6) ───────────────────────────────
#>
#>    series  alarm  alarm_date
#>   series1    160         160
autoplot(res)
#> Warning: Removed 2 rows containing missing values or values outside the scale range
#> (`geom_segment()`).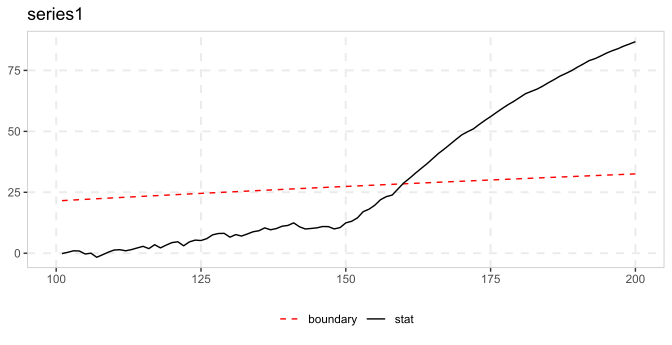
# Volatility-robust "CUSUMV" variant (Astill, Harvey, Leybourne, Taylor & Zu 2023):
# the same bubble, but volatility triples at t = 120, after the training window
y_vol <- sim_psy1(n = 200, te = 150, tf = 200, seed = 7,
  e = sim_vol_break(199, tau = 0.6))
res_kernel <- monitor_cusum(y_vol, r_star = 0.5, type = "kernel")
autoplot(res_kernel)
#> Warning: Removed 2 rows containing missing values or values outside the scale range
#> (`geom_segment()`).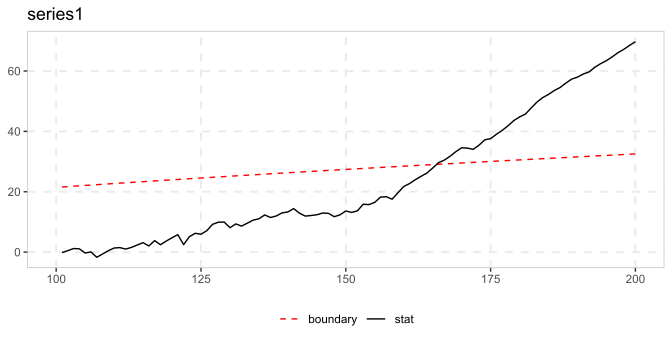
See also
monitor for the monitoring alternative based on the recursive ADF (Family A).
Other monitoring: monitor(), monitor_lbi(), monitor_quantile()
References
Homm, U., & Breitung, J. (2012). Testing for speculative bubbles in stock markets: A comparison of alternative methods. Journal of Financial Econometrics, 10(1), 198-231.
Chu, C. S. J., Stinchcombe, M., & White, H. (1996). Monitoring structural change. Econometrica, 64(5), 1045-1065.
Astill, S., Harvey, D. I., Leybourne, S. J., Taylor, A. M. R., & Zu, Y. (2023). CUSUM-based monitoring for explosive episodes in financial data in the presence of time-varying volatility. Journal of Financial Econometrics, 21(1), 187-227.