 exuber
Real-time monitoring
Quantile Unit Root Test for Bubble Detection (Global Test)
quantile_test
Replication record →
quantile_test(
  data,
  tau = "optimal",
  tau_grid = seq(0.2, 0.8, by = 0.05),
  nrep = 1000L,
  sig_lvl = 95,
  seed = NULL
)
quantile_test implements the "global test" of Wu, Shi & Wu (2025). It is a quantile-regression (QR) analogue of the Dickey-Fuller t-ratio, and it tests for explosive behavior at a chosen conditional quantile tau of y_t given y_{t-1}, and not at the conditional mean. It is a single static test and not a recursive scan. The comparable statistic in radf is the single-shot adf statistic and not the recursive bsadf.
Arguments
| data | A univariate or multivariate numeric time series object, a numeric
vector or matrix, or a data.frame. A column may have leading or trailing
NA values, which describes an unbalanced panel in which series enter or
exit the sample at different times. Those periods are filled with NA in
badf and bsadf and excluded from the adf, sadf and
gsadf of that series. Interior NA values (a gap in the middle of
a series) are not supported. When any series is padded in this way, the panel
statistics (bsadf_panel and gsadf_panel) are not available, and
the function returns NA for them with a warning. |
| tau | Quantile to test at, in (0, 1), or "optimal" (default)
to select it with the grid search of eq. 33. |
| tau_grid | Grid searched when tau = "optimal". The default
seq(0.2, 0.8, by = 0.05) matches the practical range that the paper
recommends, which excludes the extreme quantiles 0.1 and 0.9. |
| nrep | Number of Monte Carlo replications for the critical value. |
| sig_lvl | Significance level, one of 90, 95, 99. |
| seed | Optional seed for the Monte Carlo draws. |
Value
An object of class quantile_test_obj: a list with the test statistic tstat, the selected tau, the estimated correlation delta, the simulated crit value and detected (logical, tstat > crit).
Details
tau = "optimal" (the default) selects the quantile that minimizes the asymptotic variance of the QR estimator (their eq. 33) by grid search over tau_grid. The grid excludes the extreme quantiles, which the paper itself recommends avoiding at practical sample sizes.
The function simulates the critical value in each call and does not use a fixed table. There is currently no reusable exported cv counterpart for this function. This gap is tracked separately and is not addressed here. The limiting null distribution of the statistic is sqrt(1 - delta^2) * z + delta * Q, where z ~ N(0, 1), delta is a correlation coefficient estimated from the data, and Q is the standard demeaned Dickey-Fuller t-statistic distribution. The function simulates Q with the same random-walk-plus-OLS t-statistic construction used elsewhere in this package (see radf_mc_cv).
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
# Heavy-tailed (t3) innovations, where a quantile test is more useful than a test of the mean
y <- sim_psy1(n = 100, seed = 1, e = sim_innov(99, dist = "t", df = 3))
res <- quantile_test(y, nrep = 100, seed = 1)
print(res)
#>
#> ── quantile_test (n = 100, sig_lvl = 95%) ──────────────────────────────────────
#>
#>    series   tau  tstat    crit  delta  detected
#>   series1  0.25  4.684  0.6824  0.379      TRUE
autoplot(res)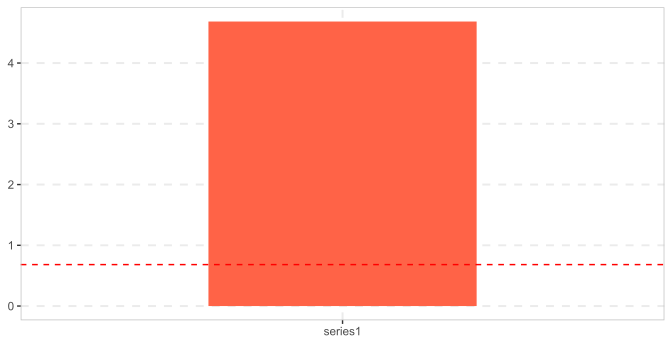
# Test at a fixed upper quantile instead of the optimal one
autoplot(quantile_test(y, tau = 0.9, nrep = 100, seed = 1))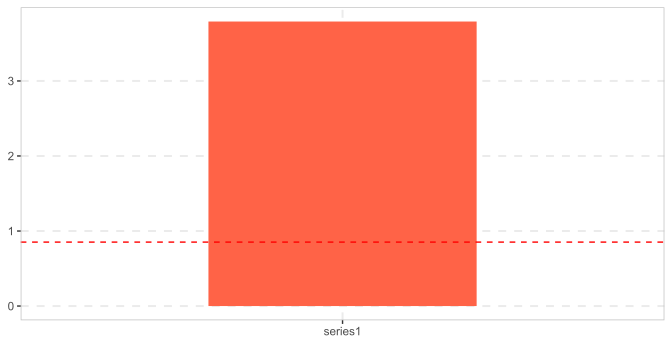
See also
radf for the family of tests based on mean regression (ADF, SADF and GSADF) that this test complements.
Other alternative tests: lbi_test()
References
Wu, R., Shi, S., & Wu, J. (2025). Quantile analysis for financial bubble detection and surveillance. Journal of Time Series Analysis, 46(5), 908-931.