 exuber
Volatility-robust (other routes)
Sign-Based Bubble Test (sPWY / sPSY)
radf_sign
Replication record →
radf_sign(data, minw = NULL)radf_sign computes the sign-based variant of the recursive right-tailed unit root test of Harvey, Leybourne & Zu (2020). Instead of applying the (double-)supremum ADF test to the series itself, it applies it to the cumulated sign of the first differences, C_t = sum(sign(diff(y))). The sign() function removes all information about magnitudes, so the recursive DF statistic of C_t is exactly invariant to the pattern of volatility in the innovations, even when volatility changes over time. Unlike radf, the test needs no wild bootstrap to control its size under heteroskedasticity. The critical values in radf_sign_cv are pivotal, so they are computed once and not for each dataset.
Arguments
| data | A univariate or multivariate numeric time series object, a numeric
vector or matrix, or a data.frame. A column may have leading or trailing
NA values, which describes an unbalanced panel in which series enter or
exit the sample at different times. Those periods are filled with NA in
badf and bsadf and excluded from the adf, sadf and
gsadf of that series. Interior NA values (a gap in the middle of
a series) are not supported. When any series is padded in this way, the panel
statistics (bsadf_panel and gsadf_panel) are not available, and
the function returns NA for them with a warning. |
| minw | A positive integer. The minimum window size (default = , where T denotes the sample size). |
Value
An object of class radf_sign_obj/radf_obj. It is the same adf/badf/sadf/bsadf/gsadf list as for radf, computed on the sign-transformed series, and it pairs with radf_sign_cv.
Details
The price of this invariance is power. The paper finds that the sign-based test outperforms the standard PSY test for many specifications of time-varying volatility and bubbles, but not for all of them, and the standard test can still win in some. The strategy that the paper recommends in practice is a bootstrap-based union of rejections that combines both tests. We have not implemented it (see the package's enhancement notes for the cost and benefit considerations), and this function provides the standalone sign-based test only. sadf is the single-supremum sPWY statistic (r1 = 0 fixed), and gsadf is the double-supremum sPSY statistic.
Level-shift robustness
Harvey, Leybourne, Tatlow & Zu (2025) show that this test keeps its standard null distribution, the one without level shifts, in the presence of deterministic level shifts, provided that the number of shifts grows strictly more slowly than sqrt(T). The size of the shifts does not matter. This is a materially weaker requirement than the one the standard PSY test needs for size control, which restricts the number and the magnitude of the shifts jointly. In their simulations the standard test is never correctly sized once the number of shifts grows at rate sqrt(T), while this test stays close to its nominal size.
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
# Volatility triples half-way through the sample. This is the case of
# non-stationary volatility that this test is built for, and plain radf()
# over-rejects here
y <- sim_psy1(n = 200, seed = 1, e = sim_vol_break(199))
res <- radf_sign(y, minw = 20)
print(res)
#>
#> ── radf_sign (minw = 20) ───────────────────────────────────────────────────────
#>
#>    series      adf   sadf  gsadf
#>   series1  -0.2933  4.468  8.879

cv <- radf_sign_cv(n = 200, minw = 20)
summary(res, cv = cv)
#>
#> ── Summary (minw = 20, lag = 0) ──────────────── Sign-Based MC (nboot = 2000) ──
#>
#> series1 :
#> # A tibble: 3 × 5
#>   stat   tstat  `90`  `95`  `99`
#>   <fct>  <dbl> <dbl> <dbl> <dbl>
#> 1 adf   -0.293 0.855  1.32  2.06
#> 2 sadf   4.47  2.34   2.70  3.43
#> 3 gsadf  8.88  3.51   3.91  4.92
tidy(res, cv = cv)
#> # A tibble: 1 × 4
#>   id         adf  sadf gsadf
#>   <fct>    <dbl> <dbl> <dbl>
#> 1 series1 -0.293  4.47  8.88
datestamp(res, cv = cv)
#>
#> ── Datestamp (min_duration = 0) ─────────────────────────────── Sign-Based MC ──
#>
#> series1 :
#>   Start Peak End Duration   Signal Ongoing
#> 1    84   84  85        1 positive   FALSE
#> 2    87  103 122       35 positive   FALSE
#> 3   123  123 124        1 positive   FALSE
autoplot(res, cv = cv)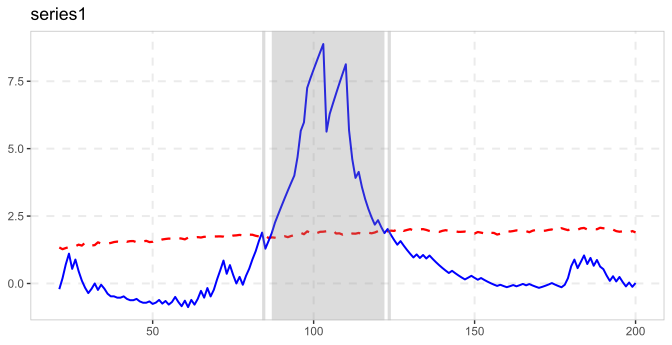
See also
radf_sign_cv for critical values, radf_sign_dm for the recursively demeaned sign-based analogue, which has the same level-shift robustness, and radf for the standard test, which is not invariant.
Other volatility-robust tests: cusum_test(), radf_kp(), radf_sbz(), radf_sbz_union(), radf_sign_dm(), radf_tt(), ssu_test()
References
Harvey, D. I., Leybourne, S. J., & Zu, Y. (2020). Sign-based unit root tests for explosive financial bubbles in the presence of deterministically time-varying volatility. Econometric Theory, 36(1), 122-169.
Harvey, D. I., Leybourne, S. J., Tatlow, D., & Zu, Y. (2025). Unit root tests for explosive financial bubbles in the presence of deterministic level shifts. Oxford Bulletin of Economics and Statistics, 87(5), 879-901. 10.1111/obes.12668