 exuber
Volatility-robust (other routes)
SBZ Weighted Least Squares Bubble Test with Union-of-Rejections
radf_sbz_union
Replication record →
radf_sbz_union(
  data,
  minw = NULL,
  nboot = 499L,
  kernel = c("gaussian", "uniform"),
  h = NULL,
  seed = NULL
)
radf_sbz_union performs the HLST (2016) wild bootstrap, the same algorithm as radf_wb_cv, jointly on the classic sup-ADF statistic (supDF, that is, the sadf of radf()) and on the WLS/kernel-volatility statistic supBZ of Harvey, Leybourne & Zu (2019). It combines them into the union-of-rejections statistic U of the paper. supBZ can have substantially higher power than supDF under many patterns of time-varying volatility, and lower power under others, for example upward volatility trends. U is designed to capture whichever of the two is more powerful for a given series.
Arguments
| data | A univariate or multivariate numeric time series object, a numeric
vector or matrix, or a data.frame. A column may have leading or trailing
NA values, which describes an unbalanced panel in which series enter or
exit the sample at different times. Those periods are filled with NA in
badf and bsadf and excluded from the adf, sadf and
gsadf of that series. Interior NA values (a gap in the middle of
a series) are not supported. When any series is padded in this way, the panel
statistics (bsadf_panel and gsadf_panel) are not available, and
the function returns NA for them with a warning. |
| minw | A positive integer. The minimum window size (default = , where T denotes the sample size). |
| nboot | A positive integer. Number of bootstraps (default = 500L). |
| kernel | Kernel for the spot-volatility estimator (eq. 6),
"gaussian" (default, as in the paper) or "uniform". |
| h | Bandwidth for the spot-volatility estimator. The default is leave-one-out cross-validation over the search range of the paper. |
| seed | An object specifying if and how the random number generator (rng)
should be initialized. It is either NULL or an integer, which is passed to
set.seed before the simulation. If you set it, the value is saved as the
"seed" attribute of the returned value. The default, NULL, leaves the state of
the rng unchanged and returns .Random.seed as the "seed" attribute. Results are
reproducible across the parallel and the non-parallel option when you use the
same seed. |
Value
A list with bootstrap p-values (p_supDF, p_supBZ, p_U) and critical values (supDF_cv, supBZ_cv, U_cv) for each series.
Details
The value of U, and not only its significance, is defined with a bootstrap-calibrated scaling ratio between the 95\% critical values of supDF and supBZ (Section 2.3 of the paper). The union also keeps its size guarantee (Theorem 3 of the paper) only if the joint bootstrap computes supDF and supBZ from the same resampled series in each replication. This coupling is why the function stays a single bundled function, and does not split into a statistic and a critical-value function as most of exuber does. supBZ alone has no such coupling, so it does split. See radf_sbz and radf_sbz_cv for the route that uses only supBZ, with the usual summary(), datestamp, tidy and autoplot pipeline.
Status
[Experimental]
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
y <- sim_psy1(n = 200, te = 120, tf = 200, c = 0.03, alpha = 0, seed = 1,
  e = sim_vol_break(199))
res <- radf_sbz_union(y, nboot = 200, seed = 1)
print(res)
#>
#> ── radf_sbz_union (minw = 27, nboot = 200) ─────────────────────────────────────
#>
#>    series  supDF  supBZ      U  p_supDF  p_supBZ    p_U
#>   series1  9.264  4.829  9.264        0    0.005  0.005
autoplot(res)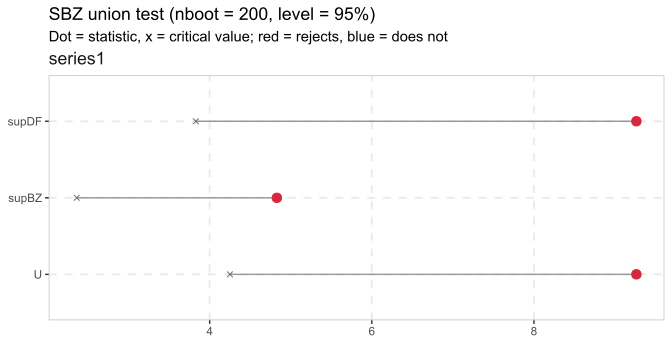
See also
radf_wb_cv for the underlying wild bootstrap, which uses supDF only, radf_sbz and radf_sbz_cv for the route that uses supBZ only and has full pipeline support, and radf_tt for a heteroskedasticity-robust alternative that needs no bootstrap.
Other volatility-robust tests: cusum_test(), radf_kp(), radf_sbz(), radf_sign(), radf_sign_dm(), radf_tt(), ssu_test()
References
Harvey, D. I., Leybourne, S. J., & Zu, Y. (2019). Testing explosive bubbles with time-varying volatility. Econometric Reviews, 38(10), 1131-1151.