 exuber
Simulation
Simulation of a stochastic branching-tree bubble
sim_tree sim_tree(
n,
a = 0.95,
eta = 1,
mu = -1,
rho = 0.7,
sigma = 4,
y0 = eta/(1 - a),
seed = NULL
)Simulates the stochastic-tree bubble process of Gourieroux & Jasiak (2025). It is a positive stationary submartingale generated by a binomial tree with stochastic branching intensity, which makes it a random-coefficient autoregression, in contrast to the deterministic branches of Cox-Ross-Rubinstein. The bubble of Blanchard & Watson (1982) (sim_blan) is the special case of constant intensity.
Arguments
| n | A positive integer specifying the length of the simulated output series. |
| a | A scalar in (0, 1) (note: is the growth rate). |
| eta | A positive scalar setting the price floor eta / (1 - a). |
| mu, rho, sigma | Parameters of the latent Gaussian AR(1) intensity process (rho in (-1, 1), sigma > 0). |
| y0 | Starting value. Defaults to the price floor eta / (1 - a). |
| seed | An object specifying if and how the random number generator (rng)
should be initialized. It is either NULL or an integer, which is passed to
set.seed before the simulation. If you set it, the value is saved as the
"seed" attribute of the returned value. The default, NULL, leaves the state of
the rng unchanged and returns .Random.seed as the "seed" attribute. Results are
reproducible across the parallel and the non-parallel option when you use the
same seed. |
Value
A numeric vector of length n.
Details
The stochastic intensity is , with a latent stationary Gaussian AR(1): Given , draw and set (the paper's eq. 5-6): controls the growth rate in the active phase of a branch, sets the price floor (Corollary 1 in the source: ), controls the persistence of the bubble-growth phase, and controls the frequency of bubbles. The process has no finite mean (Proposition 3 of the source), so occasional very large values are a feature of the model and not a bug.
The default parameters () reproduce the illustrative example of the source (Section 2.3, Figure 2).
Examples
These examples are copied from the package's own documentation and are run by R CMD check on every release.
The printed output (after #>) and the plots were produced by running them against the current package source.
sim_tree(100, seed = 123) %>%
  autoplot()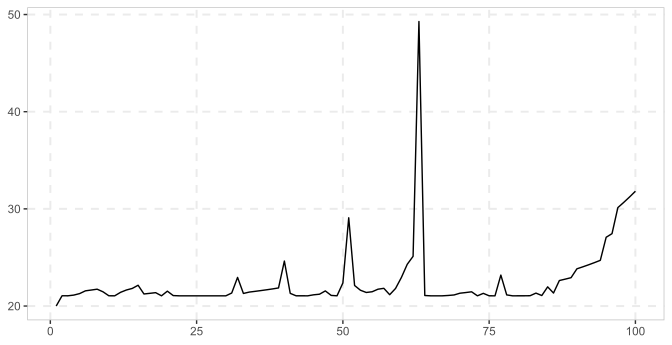
See also
References
Gourieroux, C. & Jasiak, J. (2025). "A Stochastic Tree for Bubble Asset Modelling and Pricing." JTSA, 46(5), 932-944.